N.A.M.E. National Office
Professional Association for Mobile Entertainers
Email: office@nameentertainers.net
Mail: P.O. Box 144, Willow Grove, PA 19090
for Mobile Entertainers Get Insurance Info
Insurance for Mobile Entertainers
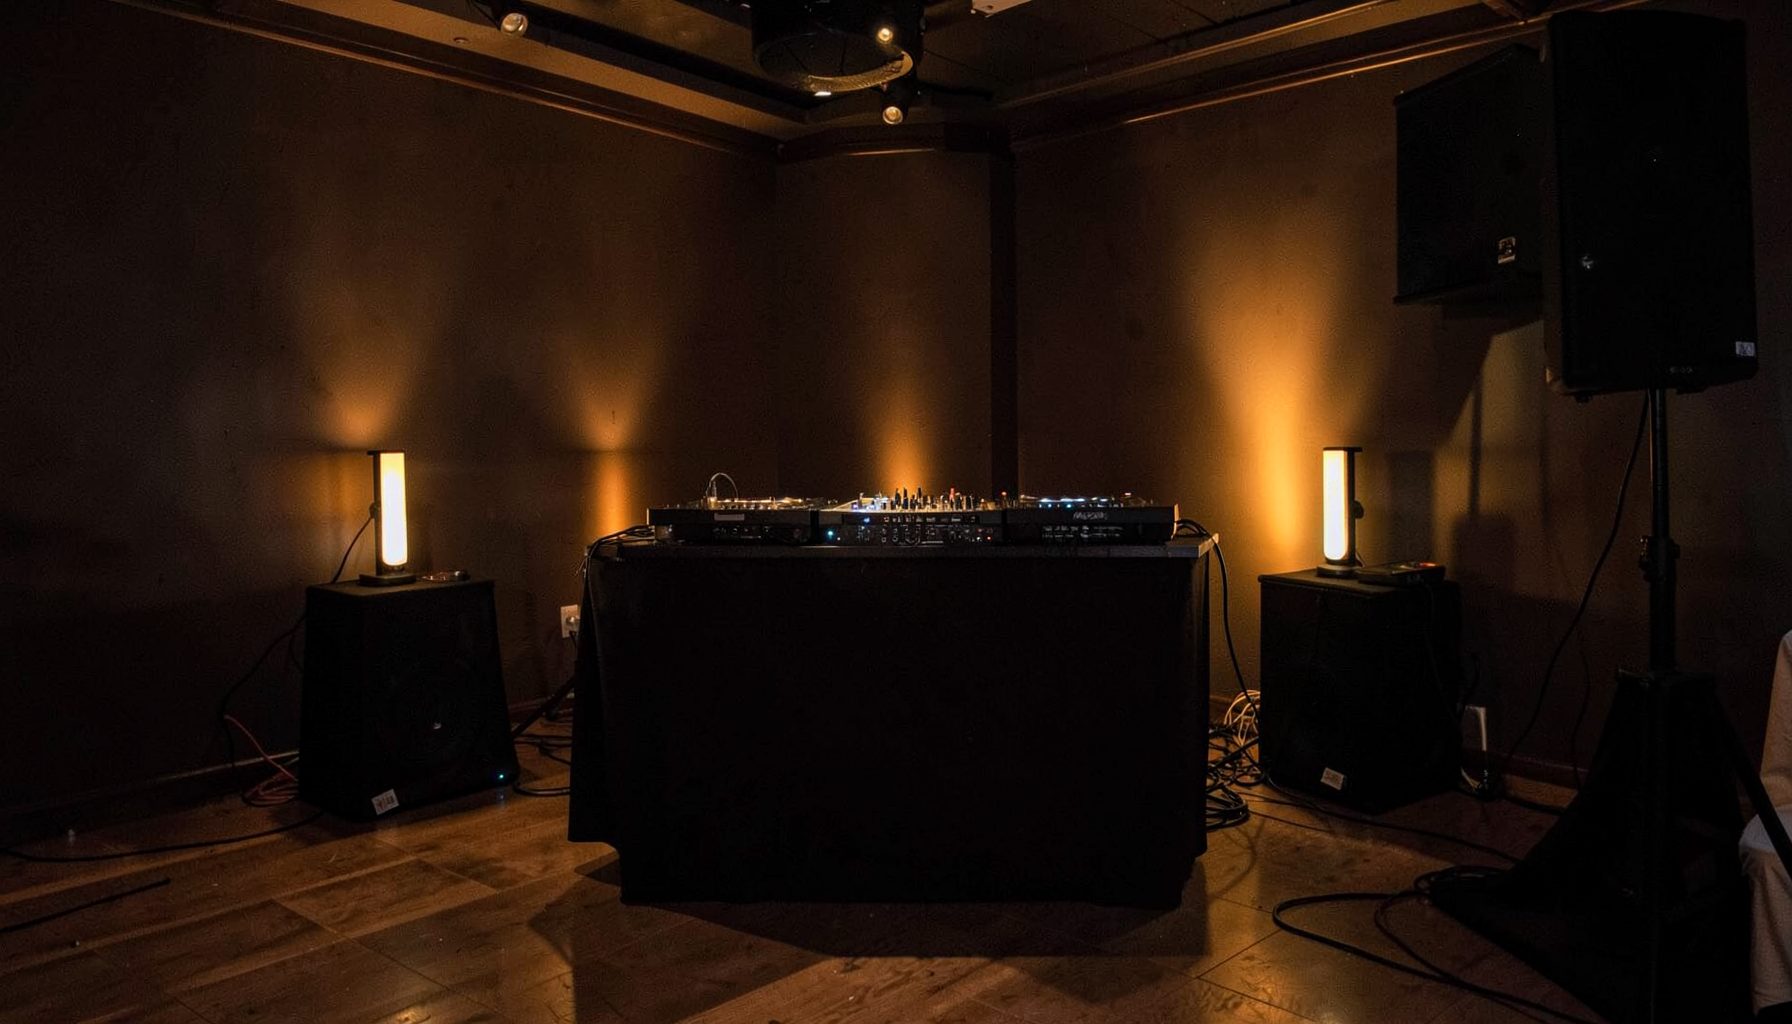
N.A.M.E. partners with Brown & Brown Insurance to offer comprehensive liability and equipment coverage designed specifically for DJs, bands, photographers, and other mobile entertainers. Coverage up to $5,000,000 is available.
Learn about insurance →News & Updates
Stay informed with the latest announcements from the National Association of Mobile Entertainers, including trade show coverage, webinar updates, and member spotlights.
N.A.M.E. publishes a monthly e-newsletter via Constant Contact featuring discounts, member benefits, and upcoming industry expos.
Sign up for the newsletter →Find an Entertainer
Search the N.A.M.E. directory of DJs and mobile entertainers who have invested in their business and uphold the quality standards of the association. Members include DJs, hypnotists, photographers, bands, event planners, booking agents, theatrical groups, and comedians.
Browse the directory →Why Mobile Entertainers Need Inland Marine Equipment Coverage
Mobile entertainers carry a business on the road. A DJ may transport speakers, mixers, microphones, lighting, laptops, controllers, cables, and backup equipment to several venues in one week. A photographer may move cameras, lenses, flashes, memory cards, and editing gear between studios, homes, hotels, and event halls. Each trip creates exposure that a standard business insurance policy may not fully address.
Commercial property insurance is usually designed for equipment kept at a listed business location. Mobile professionals have a different risk profile: their property is constantly being transported, loaded, unloaded, set up, used, and stored temporarily away from the primary premises. That is where inland marine insurance can become an essential part of a complete risk management plan.
A separate inland marine policy, or an inland marine endorsement when available, helps protect the tools that generate revenue. Understanding how this coverage works can help entertainers choose appropriate limits, avoid unexpected exclusions, and recover faster after theft, damage, or loss.
The Exposure Created By A Mobile Business
Equipment used by entertainers is exposed during every stage of an event. A speaker can fall while being unloaded, a lighting fixture can be damaged during setup, or a camera can be knocked over during a reception. Gear can also disappear from an unlocked vehicle, loading area, hotel room, or venue storage space.
The risk does not end once equipment reaches the event location. A crowded dance floor, spilled beverage, unstable power source, or hurried teardown can cause expensive damage. Because mobile entertainers often work under tight schedules, there may be little time to inspect every case, cable, stand, or accessory before leaving.
Equipment is also frequently stored in places that are not owned or controlled by the business. A DJ may keep cases in a garage, a photographer may store gear at home, and a band may use a shared rehearsal facility. Coverage should account for the way property is actually transported and used rather than assuming that all equipment remains at a permanent commercial address.
What Inland Marine Insurance Is Designed To Do
Inland marine insurance covers business property while it is being transported over land or located away from the insured’s primary premises. The name can sound confusing because the coverage generally has nothing to do with ocean travel. Historically, it developed to protect goods in transit, then expanded to cover movable property and specialized equipment.
For a mobile entertainer, covered property may include sound systems, instruments, cameras, computers, lighting, staging components, wireless systems, cases, and other tools of the trade. The policy may respond to causes of loss such as theft, fire, accidental damage, vandalism, or certain weather-related events, depending on the selected form and exclusions.
The policy wording matters. Some forms provide broad “all-risk” coverage subject to exclusions, while others cover only specifically listed causes of loss. Limits, deductibles, valuation methods, territory, unattended-vehicle provisions, and storage conditions can substantially affect a claim. A policy that looks adequate from its limit alone may still leave a significant gap if its terms do not match the entertainer’s operations.
Why General Liability Does Not Replace Property Coverage
General liability insurance is primarily designed to address claims that the business caused bodily injury, property damage to someone else, or certain personal and advertising injuries. For example, liability coverage may become relevant if a guest trips over a cable and is injured, or if a performer’s setup damages a venue’s wall.
That protection generally does not pay to repair or replace the entertainer’s own speakers, cameras, instruments, or computers. A liability policy and an inland marine policy address different categories of risk. One focuses largely on claims made by other parties; the other protects business-owned or scheduled equipment.
The distinction is important after an incident. If a thief takes a DJ’s entire sound system from a vehicle, there may be no injured third party and no damaged property belonging to the venue. Without mobile equipment coverage, the entertainer may have to absorb the replacement cost personally, even though the stolen gear is essential to completing future bookings.
Financial Protection Beyond The Equipment Price
The value of an equipment loss includes more than the original purchase price. Professional gear may have appreciated in cost, become difficult to source, or require specialized replacement. A high-end lens, wireless microphone system, or digital console can represent a large investment that is not easily replaced with a consumer-grade alternative.
A claim can also create business interruption. If a photographer lacks the right camera bodies, a band loses instruments before a booking, or a DJ has no reliable audio system, the business may need to rent substitute equipment, postpone work, refund a client, or pay additional labor. Some policies may offer limited protection for extra expenses or lost income, but those options must be specifically reviewed rather than assumed.
Accurate valuation is essential. Replacement cost and actual cash value produce different claim payments, and depreciation can be significant under an actual cash value settlement. Keeping receipts, purchase records, serial numbers, photographs, and maintenance documentation makes it easier to establish ownership and support a claim.
| Coverage concern | What it may address | Important question |
|---|---|---|
| Property in transit | Gear damaged or stolen while being moved between locations | Are loading, unloading, and vehicle storage included? |
| Equipment away from premises | Business property used at venues, homes, hotels, or temporary sites | Is coverage nationwide or restricted by territory? |
| Theft | Missing equipment following a covered theft event | Are there security requirements for unattended vehicles? |
| Accidental damage | Drops, impacts, spills, or similar incidents when covered | Are exclusions applied to wear, mechanical failure, or unexplained disappearance? |
| Replacement expenses | Costs associated with renting substitute equipment | Is extra expense coverage included or available by endorsement? |
| Newly acquired gear | Recently purchased or leased equipment | How long is temporary automatic coverage available, and what limit applies? |
Common Gaps In Mobile Equipment Policies
A basic property policy may cover equipment only at a scheduled address. That limitation can be a serious problem for entertainers whose work takes place at venues throughout a region or across the country. A separate inland marine form is often better suited to property that regularly changes location.
Another gap involves equipment that is borrowed, rented, leased, or held for someone else. A photographer may rent a specialty lens, a DJ may use a venue’s equipment, or a band may borrow an instrument for a performance. Ownership and contractual responsibility can determine whether property is covered, so these arrangements should be disclosed before a policy is issued.
Pairing equipment coverage with liability protection is also important. Inland marine insurance may protect a speaker from theft, but it does not normally address a guest’s injury caused by that speaker or stand. Mobile entertainers often need both forms of protection, along with any venue-specific requirements, hired and non-owned auto coverage, workers’ compensation, or coverage for temporary staff.
Building A Policy Around Your Actual Inventory
Start by creating a current equipment inventory. Record each item’s description, brand, model, serial number, purchase date, replacement cost, and location. Include accessories that would be costly to replace, such as flight cases, power conditioners, stands, transmitters, batteries, and specialized cables.
Consider how equipment moves through the business. Explain whether gear is transported in a personal vehicle, commercial van, trailer, or rental truck. Identify where it is stored overnight, how it is secured, whether employees or subcontractors handle it, and whether it is used by clients or other professionals. These details can affect eligibility, premiums, deductibles, and exclusions.
When a new camera, console, instrument, or lighting package is acquired, do not wait until renewal to address it. Review guidance on adding equipment mid-year so the item is reported promptly and any temporary coverage period is not misunderstood. The exact process depends on the insurer and policy terms.
Keeping Coverage Accurate As The Business Changes
Mobile entertainment businesses rarely stay static. Equipment is upgraded, revenue changes, services expand, and new employees or subcontractors may begin handling property. A policy that fit a solo DJ several years ago may be inadequate after adding event production, photography, staging, or multiple crews.
Review the schedule at least annually and after major purchases. Remove items that were sold, raise limits when replacement costs increase, and ask whether newly acquired equipment, rented gear, electronic data, or property in a vehicle receives the protection the business requires. Also verify the deductible, since a low premium can be offset by an amount the business cannot comfortably pay after a loss.
Professional associations can provide useful education while an entertainer evaluates these decisions. N.A.M.E. has served mobile entertainers nationwide since 1996 and offers insurance options alongside business consulting, educational resources, certifications, webinars, seminars, marketing support, and industry connections. Members can explore N.A.M.E. member resources as part of a broader approach to protecting and developing a mobile entertainment business.
Practical Steps For Stronger Equipment Protection
- Build a detailed inventory with photographs, serial numbers, receipts, and current replacement values.
- Ask whether the policy covers transportation, loading, unloading, temporary venues, overnight storage, and unattended vehicles.
- Separate protection for your own equipment from liability coverage for injuries or damage involving other people’s property.
- Review borrowed, rented, leased, and newly purchased equipment before using it at an event.
- Reassess limits, deductibles, exclusions, and business interruption options after major changes.
The right inland marine arrangement helps protect the working assets that make each booking possible. It can reduce the financial shock of theft, accidental damage, and transportation losses while complementing the liability coverage expected by many venues and clients.
Before the next event, compare your inventory with your current policy, identify where equipment is stored and transported, and discuss any gaps with a qualified insurance professional. A carefully reviewed policy can help keep a single damaged case or stolen equipment load from interrupting the business you have built.
Get in Touch
Contact N.A.M.E. for membership inquiries, insurance questions, or general information.